
Deeper stock market could ease interest rate pressures in Vietnam
Developing Vietnam’s stock market into a major source of medium- and long-term financing could ease pressure on banks, help stabilize interest rates and attract more international investment, financial experts said.
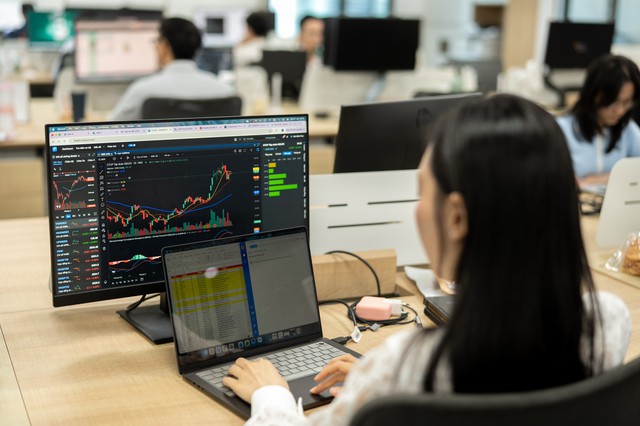
Reducing interest rates cannot rely solely on monetary policy adjustments. Photo: Huu Hanh / Tuoi Tre
Vietnam needs large, stable and long-term capital flows to sustain high economic growth. However, with bank lending still shouldering much of the economy’s financing needs, experts said a deeper capital market is essential to diversify funding sources and reduce pressure on the banking system.
Stock market needs to provide long-term capital
Tran Thi Khanh Hien, director of research at MB Securities (MBS), said deposit rates at Vietnamese banks showed mixed movements last month but generally remained at high levels.
Of the 16 banks monitored by MBS, six raised deposit rates by 0.2-0.4 percentage points for terms of six to 24 months, while four cut rates by 0.1-0.6 percentage points for terms of 12 to 24 months.
By the end of last month, the average 12-month deposit rate among the surveyed commercial banks had reached 8.45 percent per year, up 2.63 percentage points from the beginning of the year.
As of September 30, outstanding credit across the banking system had increased 11.6 percent from the end of 2025, compared with 9.8-percent growth in deposits. The gap continued to put pressure on interest rates.
Analysts at SSI Research cautioned against expecting substantial rate cuts, saying that rising bank funding costs were gradually affecting lending rates, while inflationary pressures limited the scope for broad-based reductions.
Easing rates would require deposit growth to outpace credit growth, alongside improvements in inflation and external conditions.
Truong Hien Phuong, senior director at KIS Vietnam Securities, said the challenge was not simply how much more banks could attract in deposits, but how financing demand was distributed across different channels.
When long-term investment projects rely primarily on bank loans, pressure on funding and maturity matching will be difficult to ease sustainably, he said.
“Reducing pressure on interest rates requires an additional source of medium- and long-term capital large enough to share the burden with the banking system,” Phuong said.
To attract investment, corporate earnings growth must translate into cash flow. International investors look beyond Vietnam’s GDP growth rate. Photo: Quang Dinh / Tuoi Tre
Corporate earnings key to attracting foreign capital
Vietnam also needs to expand access to international capital, particularly medium- and long-term investment, rather than relying solely on domestic funding channels.
Following FTSE Russell’s upgrade of Vietnam from frontier market to secondary emerging market status on September 21, foreign investors have continued to net sell Vietnamese stocks despite encouraging economic growth figures.
Le Tran Bao Tram, sales director at Yuanta Vietnam Securities, said this showed that economic growth and stock market capital flows did not always move in tandem.
One major factor influencing international investment decisions is the global cost of capital, she said.
When U.S. Treasury yields and borrowing costs in other developed markets remain high, investors have more opportunities to earn returns from lower-risk assets.
This can prompt portfolio reallocation away from frontier and emerging markets, particularly those with relatively small market capitalization and limited liquidity.
Higher capital costs have also changed how investors value companies.
Beyond growth prospects, investment funds increasingly focus on actual profitability, free cash flow, capital efficiency, balance-sheet quality and debt repayment capacity.
To attract foreign investment, corporate earnings growth must translate into cash flow, Tram said.
International investors look beyond Vietnam’s GDP growth rate to assess the profitability and financial health of individual businesses.
SSI Research also said that ambitious economic growth targets require better project selection and more efficient resource allocation.
Large companies may have advantages in implementation, but size alone does not guarantee efficiency.
Smaller businesses need opportunities to grow and access appropriate financing to contribute more effectively.
“Interest rate reductions cannot rely solely on monetary policy adjustments. When the capital market becomes sufficiently deep, some long-term investment needs can be financed through equity and bonds, easing pressure on the banking system and creating more room to stabilize interest rates,” an SSI Research representative said.
Vietnam Capital Market Forum 2026 to take place soon
Removing barriers to attracting international capital is also a key focus of the Vietnam Capital Market Forum 2026, themed 'New Capital Flows - A New Position for Vietnam's Stock Market.'
The event is organized by Tuoi Tre (Youth) online newspaper in coordination with the State Securities Commission, with support from Tien Phong Commercial Joint Stock Bank (TPBank), Vietnam Technological and Commercial Joint Stock Bank (Techcombank), Ho Chi Minh City Development Joint Stock Commercial Bank (HDBank), Saigon-Hanoi Securities Joint Stock Company (SHS), Viettel Group, VPBank Securities Joint Stock Company (VPBankS), F88 Investment Joint Stock Company, and Van Phu Real Estate Development Joint Stock Company.
The forum will take place on the afternoon of October 30 in Ho Chi Minh City.
It will bring together representatives from regulatory agencies, FTSE Russell, investment funds, banks, securities companies, and domestic and international financial experts.
The discussion session titled 'Vietnam Welcomes Global Capital Flows' will focus on identifying barriers to foreign investment, including foreign ownership limits, market accessibility, trading and settlement mechanisms, and foreign exchange risk management.
Speakers will also discuss solutions to capitalize on opportunities following Vietnam's upgrade by FTSE Russell and continue improving conditions to meet MSCI's upgrade criteria, thereby enhancing the stock market's attractiveness and drawing long-term international investment capital.
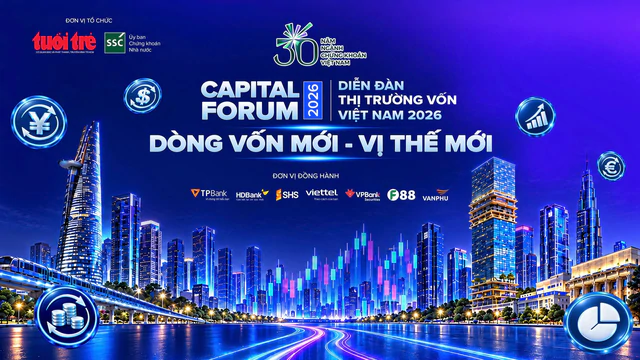
Minh Duy - Binh Khanh - Thanh Tuyen / Tuoi Tre News
Link nội dung: https://news.tuoitre.vn/deeper-stock-market-could-ease-interest-rate-pressures-in-vietnam-10326102821595789.htm