While recent improvements in business conditions have been observed, business leaders are maintaining a cautious outlook as the market’s downward trend is far from over.
Optimism in export market
The wood sector, a cornerstone of Vietnam’s exports, has experienced a gradual resurgence in new orders following a prolonged contraction. Nguyen Quoc Khanh, chairman of the Handicraft and Wood Industry Association of HCMC (HAWA), noted that the uptick in fresh orders may align with the demands of the year-end global shopping spree for interior and exterior furnishings. Although the order volume has not rebounded as strongly as expected, it ignites hope for the industry to meet its export target.
Similarly, Vietnam’s seafood sector is displaying signs of improvement. Data from the Vietnam Association of Seafood Exporters and Producers (VASEP) indicate that fishery export value in the January-July period grew a significant 25% against the same period in 2022. However, the pace of decline has slowed, with a year-on-year drop of 11% in July alone, amounting to US$830 million in seafood export value.
Anticipating an economic rebound in major markets in the coming months, coupled with resurging demand for imports in economic powerhouses like the U.S. and China, the export landscape is tilting favorably. Depleting stocks and inventories, combined with increased demand due to year-end festivities, contribute to this trend.
VASEP noted that financial support for domestic seafood exporters and improved business conditions have ensured consistent access to raw materials and enhanced export pricing, bolstering the competitiveness of seafood exporters in the global market.
Buoyed by these promising developments, VASEP projects a robust seafood export figure exceeding US$4 billion in the remaining five months of the year, elevating the 2023 total to an estimated US$9 billion.
Despite the current low order volume, the textile and garment sector is expected to experience a resurgence. Recent data indicates a 4.1% uptick in overall export value in July compared to the previous month, totaling US$3.65 billion. This follows a 13.2% month-on-month increase in June.
Discussing the sector’s outlook for the year’s end, an analyst from securities brokerage VNDirect envisions a brighter trajectory for the high-end textile segment, particularly fibers, starting from the third quarter. The upcoming year-end festive season is expected to catalyze robust activity in the fourth quarter.
“The demand for textile products tends to surge in the final months of the year to coincide with celebrations and festivals. We anticipate livelier export activity for upper-tier products starting in the third quarter of 2023,” the VNDirect expert stated.
VNDirect anticipates a gradual recovery across the three segments of the value chain – upstream, midstream, and downstream – in the latter half of 2023, driven by mid-term and long-term supporting factors. Challenges in the textile sector are approaching resolution, with the fiber sub-sector leading the way in recovery, according to the securities brokerage firm.
Persisting challenges
The latest release from S&P Global Market reveals that the decline in Vietnam’s manufacturing sector continues. The S&P Global Vietnam Manufacturing Purchasing Managers’ Index, a measure of manufacturing activity, showed a modest increase of 2.5 points in July compared to June, reaching 48.7 points. Although still below the 50.0 no-change mark, this reading indicates a sustained decline in the health of the manufacturing sector. However, it marks the mildest monthly drop this year. The index ranges from 0 to 100, with a reading above 50 indicating an overall increase and below 50 signifying a decrease in sector performance compared to the previous month.
While Vietnam’s manufacturing sector remained in contraction territory in July, signs of stabilization emerged. Production levels, new order placements, and employment contraction showed slower rates, and business confidence improved.
“There were indications that demand might be stabilizing, as new orders edged down at the slowest pace in five months. Firms are hopeful that this trend will lead to renewed growth in orders in the coming months,” said Andrew Harker, director of economics at S&P Global Market Intelligence.
The Index of Industrial Production (IIP), released by the General Statistics Office, supports these observations. In July, the IIP increased by 3.9% over the previous month. This upswing coincided with a rise in exports. Meanwhile, the overall import value surged to US$27.53 billion, a 4.4% month-on-month increase. Experts view this growth in import volumes as a positive sign, particularly as imports revolve around production materials, suggesting potential export growth in the near future.
Indeed, export figures have been rising for the past three consecutive months, accelerating month over month, except for April, thanks to robust trade promotion activities.
However, amid these positive signals, challenges persist. In the short term, smaller order volumes require greater product diversification and swift adaptation. Nguyen Van Sang, director of furniture exporter Viet Products, predicts a full recovery to pre-pandemic levels may not happen until mid or late 2024. Although orders from Europe and the U.S. have trickled in for year-end shopping, their scale remains limited, impacting the overall recovery pace.
The garment industry echoes a similar story. Pham Van Viet, chairman of Viet Thang Jean Company, noted that the company had increased operations to 80% capacity in preparation for the year-end shopping season and the Lunar New Year festival. However, fresh orders remain subdued due to challenges in consumer markets.
According to Pham Xuan Hong, chairman of the HCMC Association of Garments, Textiles, Embroidery, and Knitting, the business environment for the year-end remains unpredictable, and market movements have not yet become evident. Most association clients are currently adopting a cautious strategy, monitoring market dynamics, consumer demand, and inventory levels before taking any action.
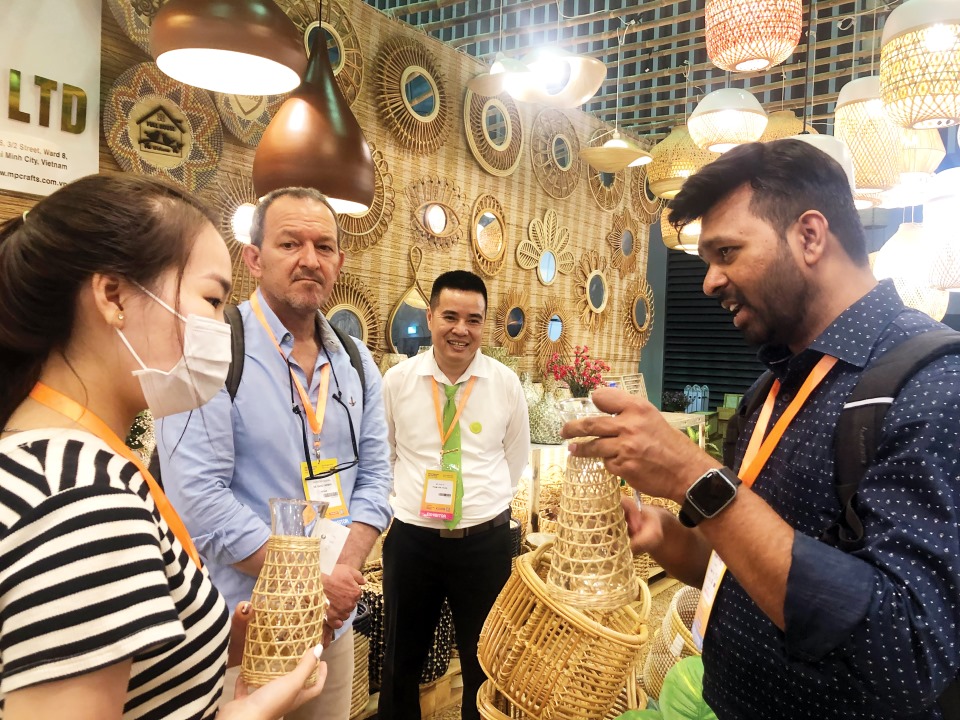
Despite ongoing difficulties in export markets, there is a silver lining – businesses are leveraging free trade agreements (FTAs) to sustain exports to key markets. Participation in international trade fairs is also a prevalent strategy to secure customers and tap into new markets.
In the current market condition, enterprises are advised to be proactive, adapt product styles and designs to consumer preferences, ramp up marketing efforts, maintain high-quality standards, and manage competitive pricing.
Drawing on lessons from past recessions, Tran Si Chuong, a development economist, business strategist, and member of the UK’s strategy consulting firm 3Horizons, believes that growth opportunities are attainable for both the furniture industry and the global economy despite current setbacks.
According to him, a combination of negative global factors has prompted operational changes. Companies need adaptive strategies by enhancing internal capabilities to navigate these changes effectively and prepare for increased market demand in the future.
One significant change is that product sustainability has evolved from being optional to becoming a mandatory requirement for market participation. Embarking on a sustainable transformation now holds the key to enhanced competitiveness.