Despite a high probability of market corrections due to profit-taking pressure and geopolitical tensions in several parts of the world, these conditions can also present opportunities for investors. Strategic buying in positively evaluated sectors could set up portfolios for growth in the next cycle.
Pressure before the resistance zone
Vietnam's stock market is currently experiencing volatile movements, with the VN-Index stuck at the 1,300-point resistance level for over a month. This stagnation reflects investor caution amid a mix of favorable and unfavorable news. Even though positive macroeconomic data and the Q3 earnings season have offered some support, concerns about recent developments continue to linger.
Geopolitical tensions, particularly in the Middle East, have adversely affected global financial markets. These uncertainties have driven capital flows towards safer investment avenues, such as gold and the U.S. dollar, instead of riskier assets like stocks. The U.S. Dollar Index has surged to a three-month high of 104 points, while global gold prices are nearly at a record high of over US$2,700 per ounce.
At home, the VN-Index's repeated inability to break through the 1,300-point resistance has prompted many investors to take profits, putting the pressure on the market. For example, after consistent net buying in late September and early October, foreign investors turned net sellers, offloading over VND3.78 trillion of shares between October 4 and 21.
With the exchange rate between the Vietnamese dong and the U.S. dollar showing renewed signs of tension, it is understandable why foreign investors have resumed net selling. Historically, exchange rate volatility has significantly impacted the stock market. Recently, the bank-quoted dollar price has surged dramatically, nearing the levels seen on the informal market, while domestic gold prices have also risen, placing a further strain to the exchange rate.
The dollar spike came unexpectedly, given earlier forecasts that it would weaken due to expectations that the U.S. Federal Reserve (Fed) would make interest rate cuts in the last two months of 2024.
In response to the risk of the dong depreciation, the State Bank of Vietnam (SBV) has resumed net withdrawals via open market operations and Treasury bills. From October 1 to October 21, nearly VND105 trillion was pulled from circulation. Notably, on October 18 and 21, the SBV issued VND33.95 trillion of Treasury bills after a two-month break. If this trend continues, it could negatively impact interest rates, especially during the year-end period when liquidity in the financial system typically comes under significant pressure.
Which sectors to watch in the next growth cycle?
Although there is still a high likelihood of market corrections due to profit-taking and geopolitical tensions, this can also present opportunities for investors. They may consider increasing their stake in well-performing sectors, positioning themselves in the next growth wave, typically seen in the final months of the year and early in the following year. There are also rising expectations that Vietnam's stock market could be upgraded by FTSE in 2025, possibly as early as March or later in September.
Stocks in the technology and telecommunications sectors remain top picks for many investors, thanks to their robust growth potential amid the ongoing trend of digital transformation. Investment in these sectors not only meets the growing demand for digital services but also aligns with global technological trends. The rise of 5G networks, alongside advancements in artificial intelligence, cloud computing, and smart transportation, opens significant opportunities for companies in this field to expand and innovate.
Vietnam's strategic partnerships with major economies continue to make it an attractive destination for foreign direct investment (FDI), especially in manufacturing. As demand for manufacturing and logistics space grows, industrial real estate stands to benefit, particularly with the acceleration of transport infrastructure projects. It is highly expected that the Government will soon unlock more land resources for industrial parks, further supporting this sector's growth.
The construction and building materials sector stands to benefit as the Government boosts work on key infrastructure projects. With the handover of the second phase of the North-South Expressway expected in late 2024 or early 2025, infrastructure developers could see significant gains. This ongoing development indicates a promising recovery for companies in this sector.
A positive macroeconomic outlook, bolstered by expansionary monetary policy, creates opportunities for growth in the food and beverage (F&B), and retail sectors. Large companies in these fields are aligning with consumer trends, such as the shift toward healthier products and increased online shopping, to lay the groundwork for sustained growth. Moreover, easing trade policies and improving demand from key trading partners could further boost the performance of import-export enterprises in these industries.
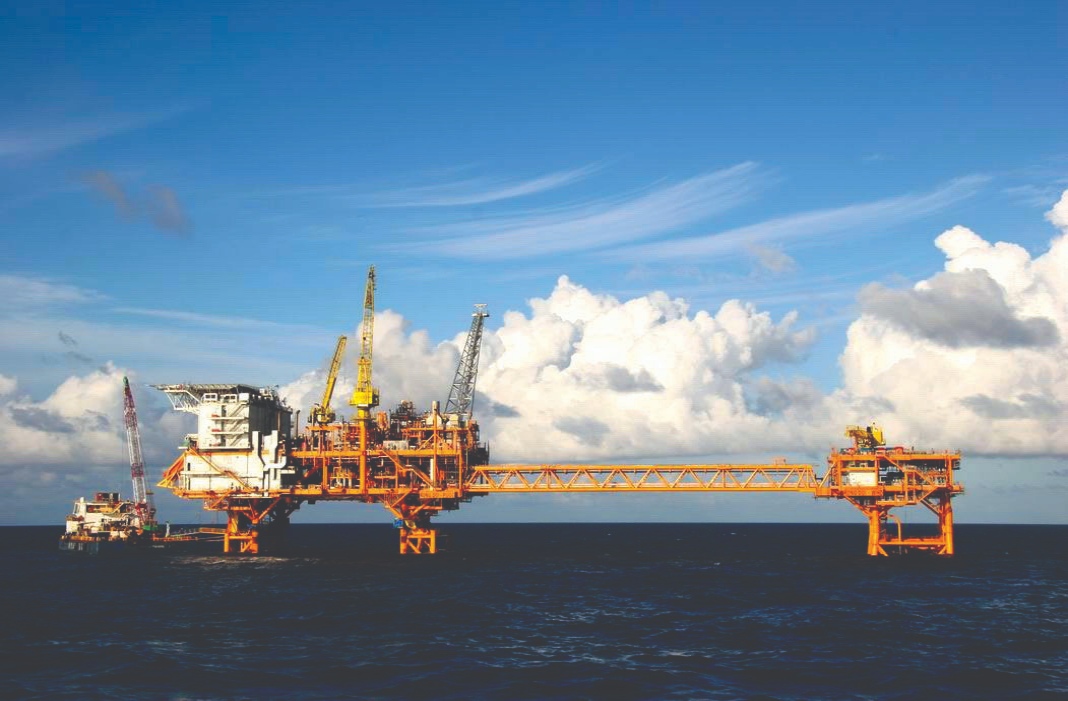
Energy stocks, particularly in the oil and gas sector, are poised for advancement. Expectations of rising global oil prices due to escalating tensions in the Middle East could drive the sector forward. Additionally, local companies may see growth if significant projects, like the Block B-O Mon initiative, begin moving forward.
Electricity stocks are likely to attract investor attention, especially as the Government focuses on boosting energy infrastructure to address supply issues, crucial for maintaining foreign direct investment (FDI) appeal. Recent moves by the Ministry of Industry and Trade to revise parts of the National Power Development Plan VIII—expanding solar and hydropower projects—signal a broader push for investment in this sector. Furthermore, retail power prices were adjusted upward by 4.8% on October 11, aligning with efforts to create a competitive power market and encourage further investment.