After making significant progress in its “financial inclusion” plan through accelerated digitalization, experts say Vietnam should now aim higher. The country needs to move beyond mere access to financial services and focus on the broader concept of “financial health.”
In Vietnam, “financial inclusion” has been a widely discussed term in recent years. The term refers to the idea that everyone should be able to access financial services.
The year 2025 marks the end of the first phase of Vietnam’s National Strategy on Financial Inclusion to 2025, with a vision toward 2030, approved in 2020 by the prime minister in Decision No. 149. The second phase, introduced by the State Bank of Vietnam, emphasizes “Digital Financial Inclusion,” highlighting how technology can improve access to financial services.
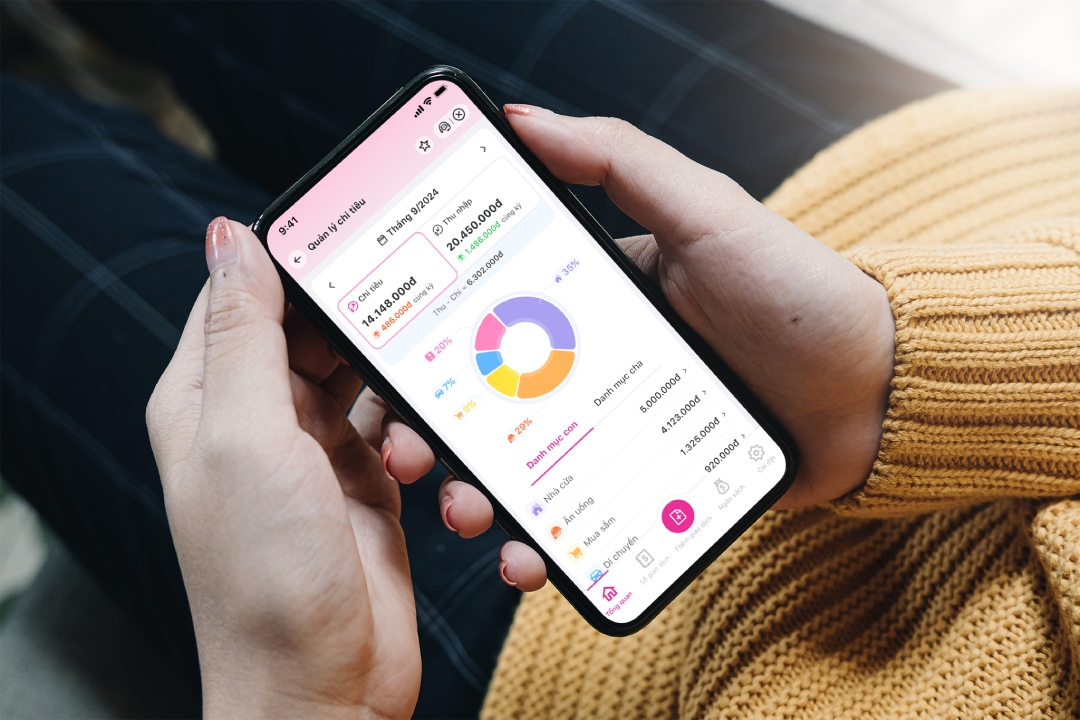
Today, Vietnamese people can easily make mobile payments almost anywhere, including rural areas, where data coverage has expanded widely. Opening accounts and paying for services have also become easier thanks to electronic authentication systems.
According to the World Bank Group’s Global Findex 2025 report, over 70% of Vietnamese adults aged 15 and older have a financial account, and 62% of them use digital payment services, thanks to internet coverage reaching 80% of the population.
Despite these achievements, Vietnam’s financial sector still faces gaps in credit access, according to experts at the Digital Finance Inclusion Conference 2025. The event was held in late October by the International Finance Corporation (IFC).
IFC experts stressed that Vietnam should take the concept of “financial inclusion” a step further toward “financial health.” This can be understood as the ability of an individual, business, or household to manage current financial obligations while having confidence in their future financial situation.
From this perspective, financial health goes beyond access; it aims to improve quality of life and help people achieve concrete goals such as paying for healthcare, education, or leisure, supporting business investments, increasing income, or saving for the future.
In this regard, The Saigon Times spoke with three experts—two from IFC and one data specialist from Singapore—about the shift from “financial inclusion” to “financial health,” highlighting the critical role of technology in supporting this transition.
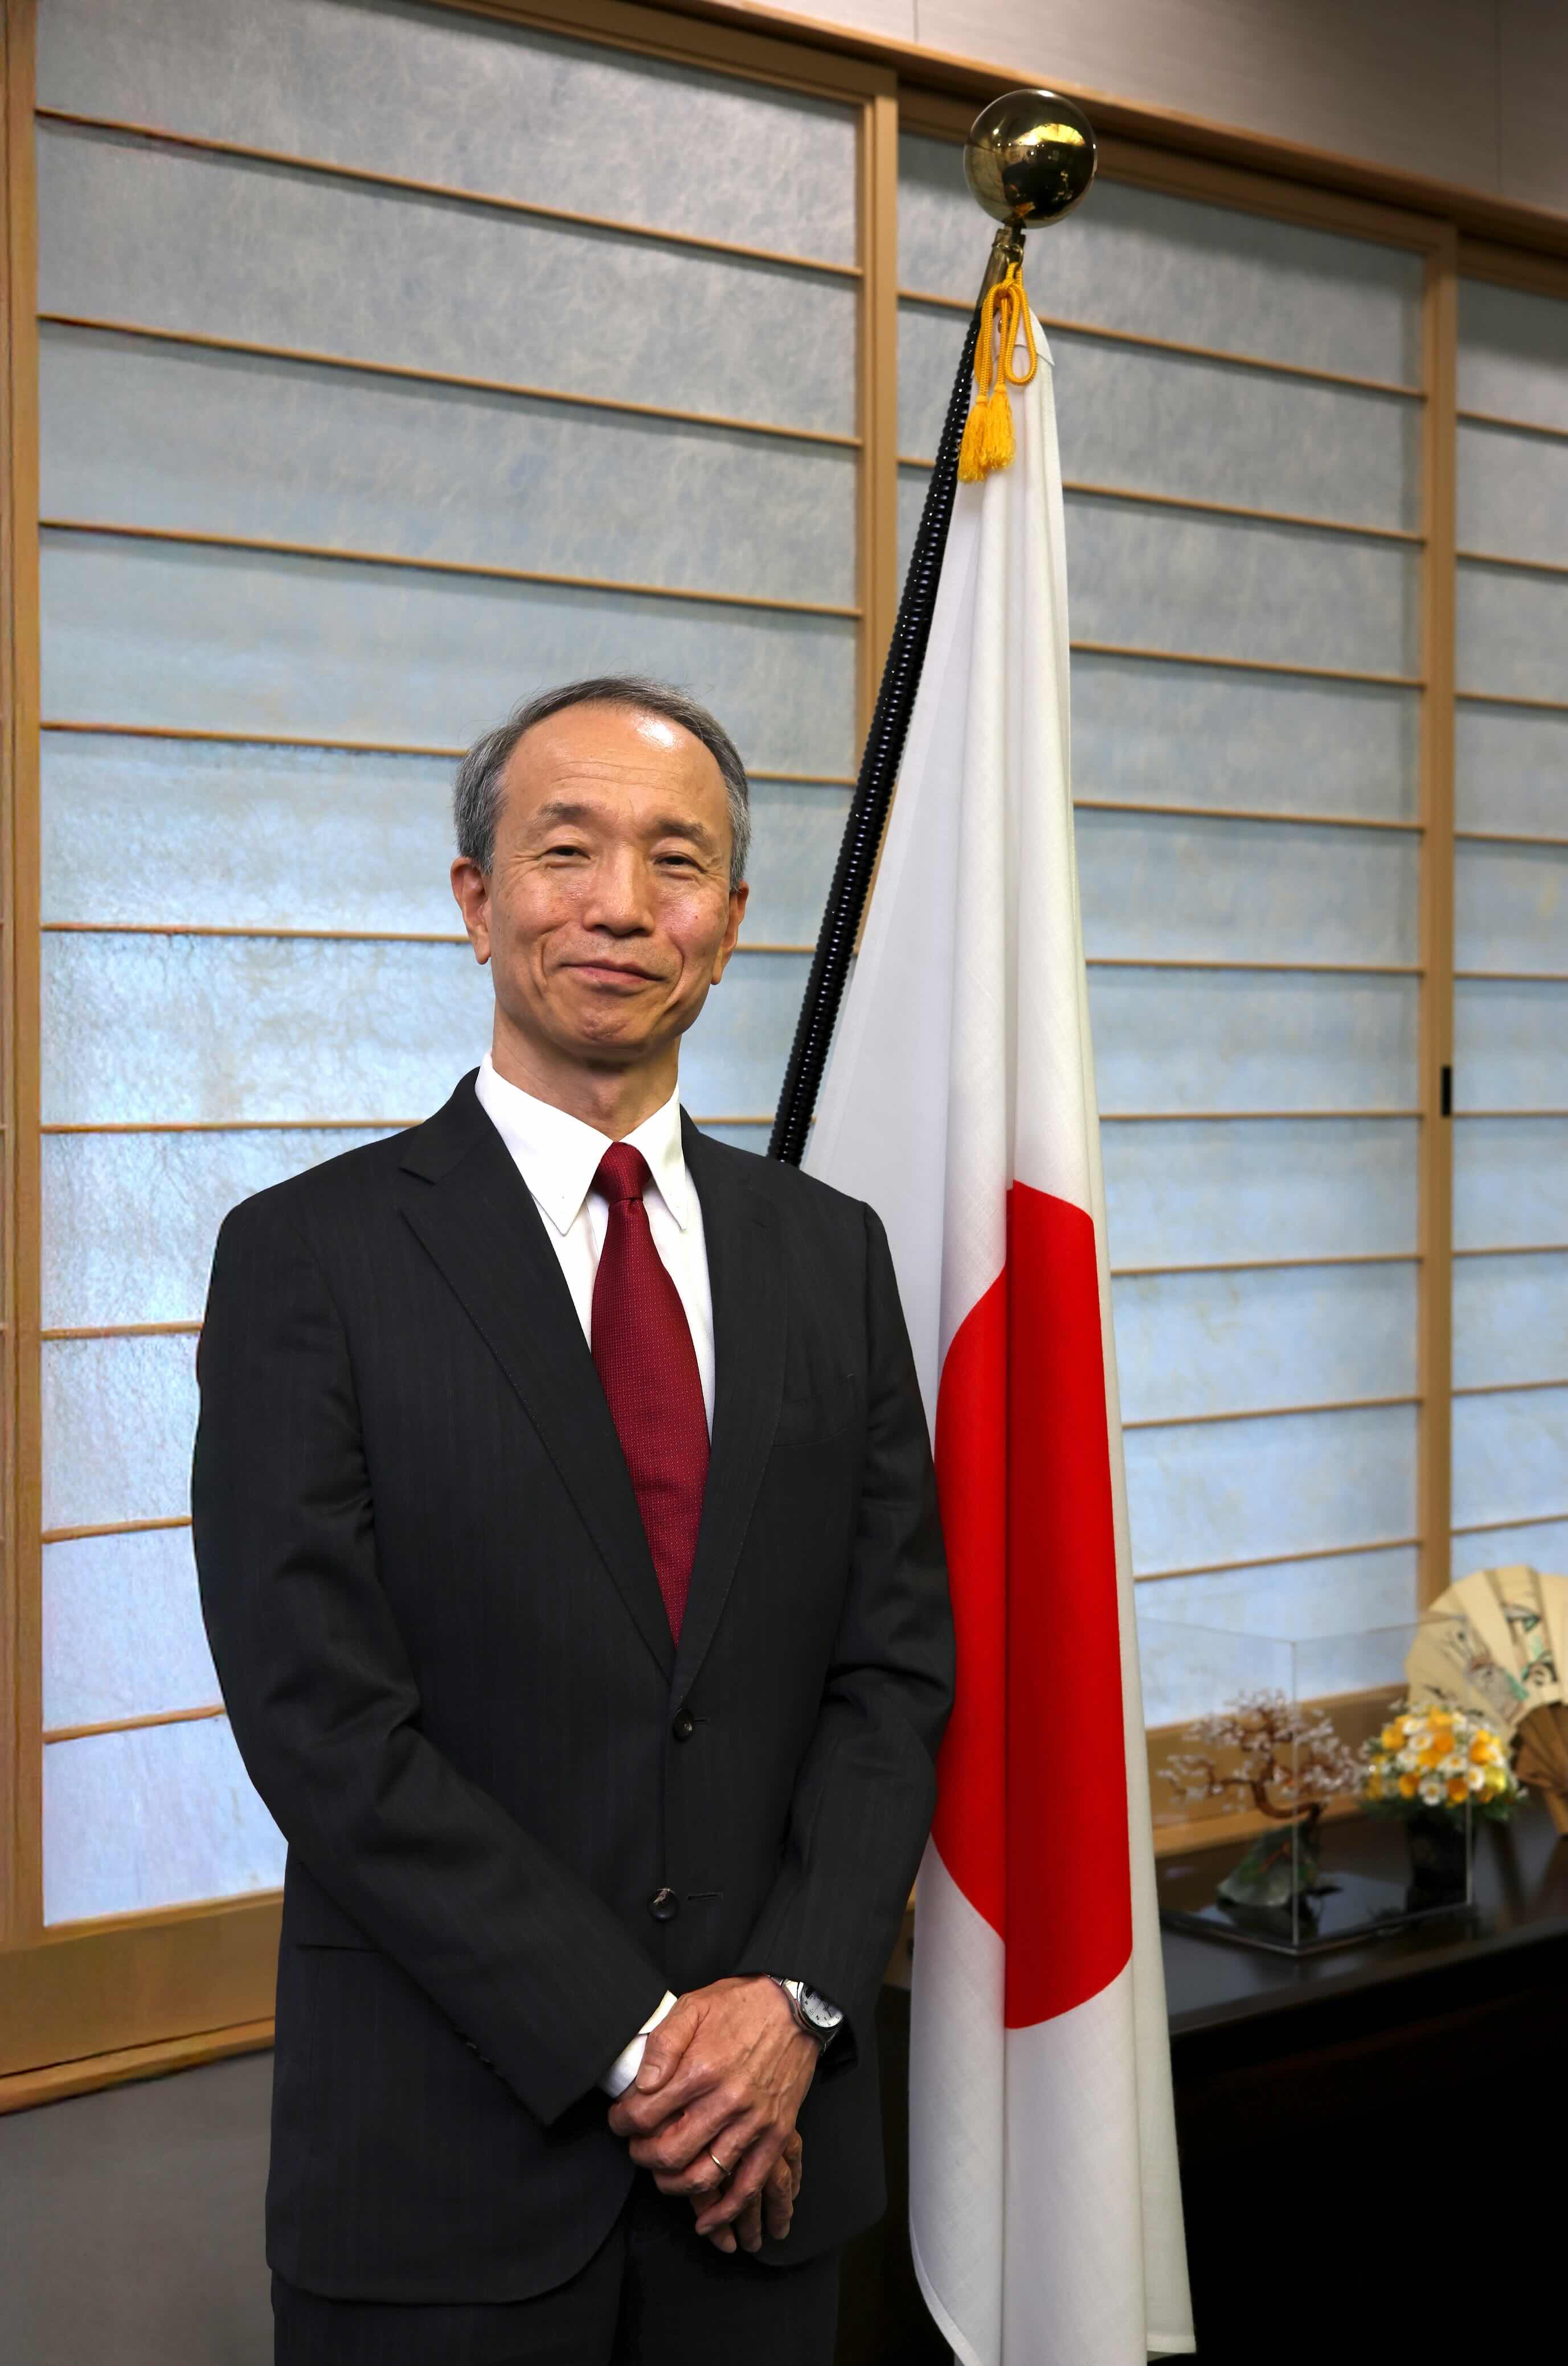
Shehryar Ali Shah, head of IFC’s HCMC Office:
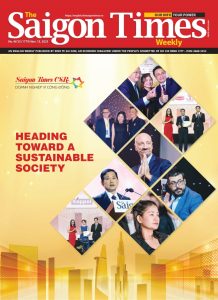
We often talk about financial inclusion and financial health. ‘Inclusion’ only ensures that people can access financial services, usually measured by the percentage of the population with bank accounts. But if those accounts always have a zero balance, it doesn’t really help.
Financial health means having the ability to use financial services effectively—such as payments, savings, or borrowing—to cover current expenses, maintain a stable life, and achieve future financial goals. That’s what really matters.
Vietnam’s financial inclusion rate is relatively high, but financial health doesn’t match that. Vietnamese users have a strong demand for financial services, yet the supply is not fully prepared to serve higher-risk groups. The key challenge is: who will lend to them?”
Vietnam has the talent and infrastructure—it’s evident in the widespread use of smartphones and platforms like Momo and Zalo. The Government has also made positive strides, such as providing every citizen with a digital ID.
So, financial inclusion itself isn’t the issue in Vietnam. The challenge is financial health. If Vietnam aims to become a high-income country by 2045, financial health needs to be a priority now.
Christian Rodriguez, Senior Advisory Officer, Financial Institutions Group at the IFC:
Singapore is a wealthy country, but that doesn’t mean everyone there has access to financial services. Wealth and financial inclusion are not the same. Even in Singapore, there’s still a need to expand access for certain groups, especially low-income workers, which is similar to Vietnam.
The issue is not customer demand but whether financial institutions can serve them effectively. This depends on whether they are willing to use alternative or data-driven solutions. Currently, many banks in Vietnam still lend in traditional ways, using conventional customer assessments.
But can a home-based business be treated the same as an office-based business? We recommend banks create individualized customer profiles based on each client’s characteristics. That allows financial institutions to offer products suited to their needs.
It’s about differentiation. Data should be used not only to profile customers but also to provide them with appropriate financial services. That’s how we promote financial inclusion in companies and banks we work with.
Additionally, we provide non-financial services to support financial health. For example, small businesses need to understand the importance of accounting and proper record-keeping. For individuals taking loans or working from home, it’s crucial to understand rights and responsibilities. Failing to repay a loan can create serious problems. Financial education is therefore essential at both the personal and business level.
Dr. Xiaoli Li, Professor at Singapore University of Technology and Design (SUTD):
Data quality is critical for effective digital financial services. Errors often come from missing or incomplete data, or from outliers, which must be cleaned. This is very important.
Another challenge is that data often exists in silos, spread across different companies, making it difficult to combine. Many countries need to establish data standards and formats to make shared data usable.
Of course, privacy must be protected; we don’t share personal data, only parameters. This kind of technology is promising but not simple, though it attracts significant interest.
Some AI technologies can help protect personal data while allowing collaboration, which improves AI models. Cybersecurity is also critical. Customer data must be protected regardless of who accesses it. Governments need laws to prevent data misuse.