The Ministry of Finance has proposed amending the method for calculating personal income tax on real estate transfers, shifting from a flat 2% tax on the transfer price to a 20% tax on the profit — the difference between the buying and selling prices. This is seen as a critical step to curb speculation, increase transparency, and promote fairness in the real estate market. However, effective implementation will require robust data infrastructure and the application of technology.
A 20% tax on profit
In the draft amendment to the Law on Personal Income Tax currently open for public comment, the Ministry of Finance proposes a fundamental change in how tax is calculated on personal real estate transactions.
Specifically, personal income tax would be levied on the profit — the difference between the selling and purchase prices — rather than applying the current flat 2% tax rate on the total transfer value. The proposed tax rate is 20% of the taxable income and would apply to each transfer transaction.
Taxable income from real estate transfers would be defined as the difference between the selling price and the purchase price, after deducting reasonable expenses directly related to generating the income from the transfer.
In cases where the purchase price and related costs cannot be determined, the tax authority would apply a tax calculation method based on the selling price multiplied by a rate determined by the holding period of the property. Specifically, a property with a holding period of less than two years would be taxed at 10%; from 2 to 5 years at 6%; from 5 to under 10 years at 4%; and 10 years or more at 2%. The holding period would be calculated from the time the individual obtains the right to use or own the property (after the law comes into effect) until the time of transfer.
For properties acquired through inheritance, the tax calculation will not depend on the holding period. The tax rate will remain at the current 2%, as inheritance, according to the Civil Code, constitutes a transfer of assets from the deceased to the living, differing in nature from gifting or donating property.
The taxable income will be determined either at the time the transfer contract takes effect or when the right to use or own the property is registered — whichever comes first.
According to the Ministry of Finance, there have been frequent cases of individuals declaring a lower transfer price than the actual transaction value to reduce their tax liability, resulting in lost state revenue. In its proposal, the ministry did not elaborate on the rationale behind the new tax policy but stated: “There are suggestions to consider imposing a 20% personal income tax on profits from real estate transfers and to consider higher taxes for cases involving speculation — such as owning 3 or 4 properties in a short time — which destabilize the real estate market.”
The ministry also noted that several countries already employ personal income tax tools to raise the cost and reduce the attractiveness of real estate speculation. Some nations also apply taxes on real estate transaction profits based on the frequency of transactions and the duration between purchase and resale.
Speculative behavior will be regulated
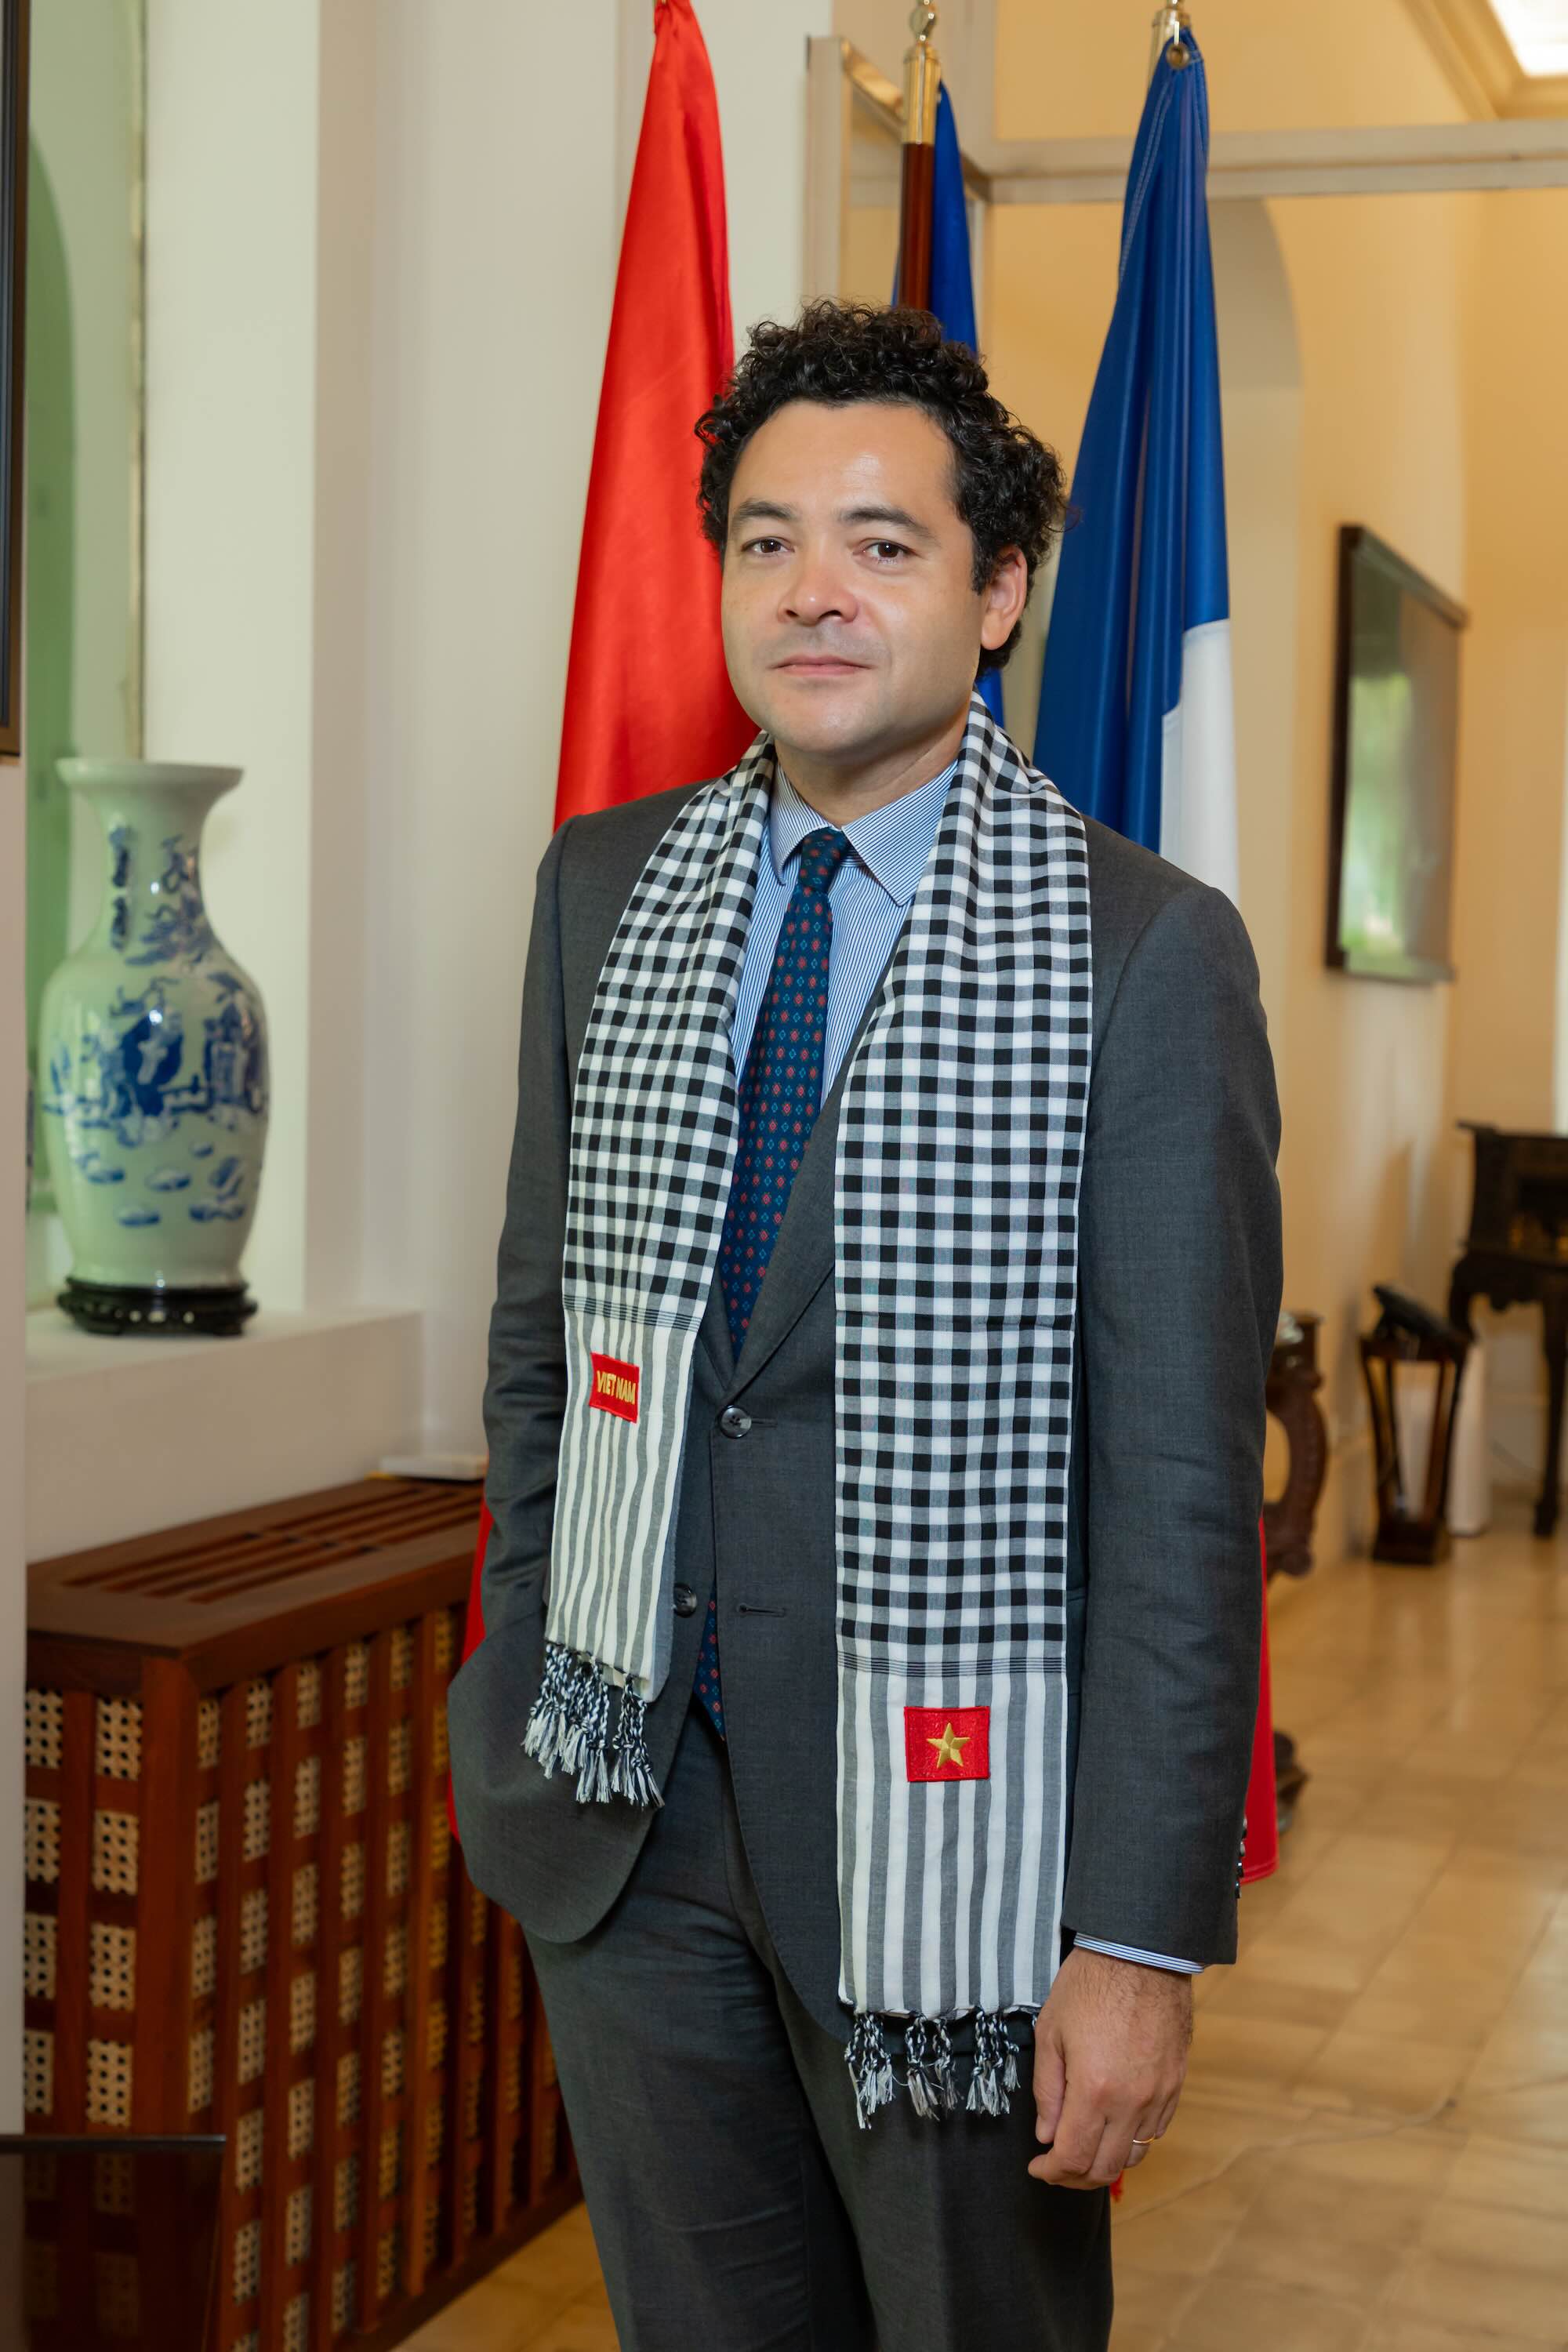
The imposition of taxes on profits from real estate transfers clearly reflects an intention to regulate speculative and short-term “surfing” activities — one of the main drivers of recent land price surges. According to National Assembly deputy Hoang Van Cuong (Hanoi delegation), former vice president of the National Economics University, shifting from a flat 2% tax on the total transfer value to a 20% tax on the price difference between selling and purchasing is a significant advancement in real estate tax policy.
The major advantage of this approach lies in establishing fairness among market participants. Pure speculators — those who buy land and hold it waiting for prices to rise — will face higher tax rates. Meanwhile, genuine investors who add value through renovation, construction, or infrastructure development will be able to deduct reasonable expenses and only pay tax on their actual gains. In this way, the tax policy serves not just as a revenue collection tool but also as a means to classify investment behaviors and guide the market toward healthier and more sustainable development.
Addressing concerns that high taxes could reduce market liquidity, Cuong emphasized the true nature of tax as a regulatory tool. “The tax policy is not aimed at squeezing the market but at preventing speculative land hoarding that distorts supply and demand,” he said. Those who use land for legitimate purposes and invest in real utility will not bear heavy tax burdens. Only those who profit from price volatility without creating real value will face stricter regulation.
However, for this policy to work effectively, significant technical challenges must be overcome — especially the accurate determination of actual purchase and sale prices. In reality, transfer contracts often do not reflect true transaction values due to sellers’ concerns over taxes, fees, and charges. The dual pricing phenomenon (declared vs. actual prices) remains widespread, especially in transactions not conducted via banks. Without a standardized, comprehensive, and updated land price database, calculating price differentials may lead to fraud, disputes, or unnecessary administrative burdens.
Particularly noteworthy is the situation in which properties transferred long ago or through multiple owners lack proper documentation or valid receipts to prove original purchase prices. In such cases, tax authorities may be forced to apply reference or default pricing, potentially disadvantaging sellers and opening the door to legal disputes.
Hoang Van Cuong believes that the fundamental condition for this policy to take effect is to address the problem of under-declaring transfer prices to evade taxes. To achieve this, it is essential to establish a transparent, objective, and regularly updated land valuation database, integrated across government agencies. At the same time, accelerating digital transformation in land and public asset management — moving toward a centralized real estate transaction database in line with international practices — will be key.
When all transactions are transparently declared and cross-verifiable, and reflect accurate market values, tax calculations will be fair, transparent, and practical.
According to Assoc. Prof. Dr. Phan Huu Nghi, deputy director of the Institute of Banking and Finance, National Economics University, the proposed 20% tax on the profit from property sales must also be accompanied by strict penalties for misreporting transaction values. This will make real estate transactions more transparent, minimize the dual pricing issue, and allow the Government to collect tax more fairly. The practice of price inflation through repeated sales and speculative brokering will also be significantly curbed.
Citing international experience, the Ministry of Finance noted that in the U.S., anti-speculation policies vary by state. In California, if a person buys multiple properties and sells them within five years, the real estate transfer tax is 24% if sold within the first year; 22% for sales between 1–2 years; 20% between 2–3 years; 18% between 3–4 years; and 14% between 4–5 years after purchase.
In Singapore, properties resold within the first year are taxed at 100% of the profit; the rate drops to 50% after two years and 25% after three years.
In Taiwan, property transactions within the first year of purchase are taxed at 15%; and at 10% if sold in the second year.
In Malaysia, under the 2014 law on real property gains tax, rates are: 30% for up to 3 years of holding; 20% for 3–4 years; and 15% for 4–5 years.