Despite facing no shortage of challenges, interest rates have remained stable since the start of the year. How will the trend evolve in the coming months, as the global economy experiences volatility but Vietnam continues to pursue strong growth targets? What factors will influence this key variable?
Signals from the market
After a downward adjustment in the final days of July 2025, the overnight interest rate on the interbank market rebounded to 5.36% on the first day of August. Compared to the 2–3% range in June, borrowing costs between banks have risen sharply and remained elevated through July, reflecting increasing liquidity pressures in the banking system.
Following a quiet period, several banks—including major ones—raised deposit rates in July. For example, Techcombank lifted deposit rates for terms of 1–36 months by 0.1–0.2 percentage point; VPBank increased the same terms by 0.1 percentage point; and Sacombank sharply raised online deposit rates for 1–5 month terms by 0.3 percentage point. Digital banks such as VCBNEO and Cake by VPBank have also recently adjusted rates upward to attract deposits.
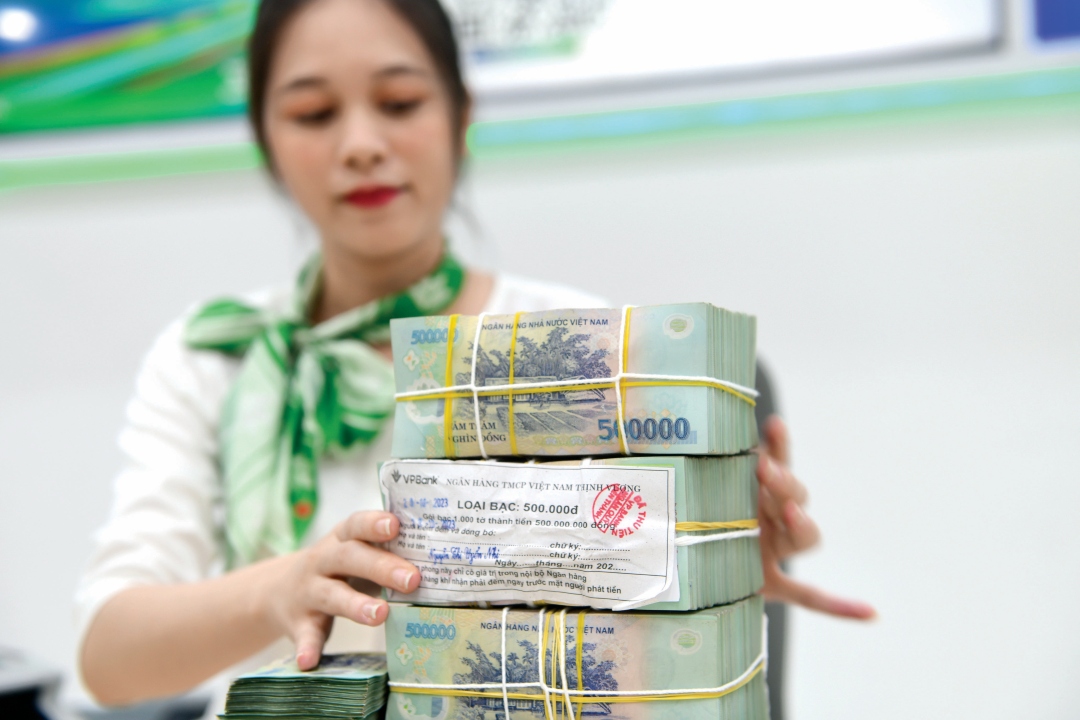
With system-wide credit continuing its strong growth trajectory since the beginning of the year, banks’ higher funding needs have pushed deposit rates upward, especially as deposit growth has not kept pace with loan growth. According to the General Statistics Office, as of June 26, 2025, deposits had grown 6.11% compared to the start of the year, while credit had risen 8.3%, leaving a raw gap of nearly VND400 trillion between the increase in deposits and credit.
Half-year financial reports from many banks also show outstanding loan growth outpacing expectations. VPBank reported an 18.6% increase in outstanding loans since the start of the year, reaching VND842 trillion; SHB posted 14.4% growth in the first half; Nam A Bank 14.7%; NCB 22%; MB 12.5%; and TPBank 11.7%. Large banks also reported strong performance, with Vietcombank up over 11%, Techcombank 10.6%, and VietinBank 10%.
Notably, according to updated figures from the State Bank of Vietnam (SBV), credit growth by the end of July had reached 9.8% compared to the end of 2024, and was up 19.75% year-on-year—a multi-year high. In response, many banks have stepped up bond issuance to boost funding and meet business expansion goals, avoiding excessive upward pressure on deposit rates.
According to the Vietnam Bond Market Association, total corporate bond issuance in nearly seven months reached more than VND286.9 trillion, with banks accounting for over 75% of the total—equivalent to more than VND215.46 trillion. However, this group also led in early redemptions: out of VND134.21 trillion worth of corporate bonds bought back early in the past seven months, banks accounted for nearly 61%, or over VND81.8 trillion.
Year-end pressure?
The possibility that credit growth will remain high is one of the factors likely to put pressure on deposit interest rates in the coming period. Analysts forecast that system-wide credit growth could reach 18–20% this year, given that by the end of July it had already reached 9.8%, even though the final months of the year are typically when loan demand surges. In recent years, credit growth has usually hovered around 14–15%.
Meanwhile, on July 31, 2025, the SBV announced an adjustment to credit growth targets for banks. This additional allocation was initiated by the SBV without requiring requests from credit institutions. Thus, to ensure the 8% GDP growth target for this year, monetary policy appears to be increasingly loosened.
Furthermore, fiscal policy could also expand at a faster pace. With the aim of boosting GDP growth even further, public investment continues to play a key catalytic role. Analysts believe that the disbursement speed of infrastructure projects in the second half of the year will increase compared to the first half of 2025, especially now that the restructuring and reorganization of administrative units has been completed and stabilized.
Accordingly, public investment disbursement is expected to reach around VND800 trillion this year, up 21% from 2024, fulfilling 87% of the plan. This also means that the money supply will have to grow faster, directly putting pressure on inflation and, subsequently, interest rates. While inflation has remained under control so far, the simultaneous intensification of both fiscal and monetary easing could lead to trade-offs in the form of higher inflation.
For depositors, when inflation rises—and with investment channels such as stocks and real estate rebounding strongly—bank deposits will need higher interest rates to remain competitive and attractive. This is not to mention other assets such as gold or foreign currencies, which have also seen sharp increases since the beginning of the year.
Take, for example, the USD/VND exchange rate. After U.S. President Donald Trump first announced reciprocal tariffs against a number of countries in early April 2025, the exchange rate has been under considerable pressure. Although recent information shows that the retaliatory tariff imposed by the U.S. on Vietnamese goods is 20%—a significant reduction from the initially announced rate—this is still high and could impact trade and investment activities in the coming period.
In the context of the USD/VND exchange rate maintaining its upward trend—particularly as the U.S. dollar strengthens again in the global market, with the USD Index rising 2% in just the past month—exchange rate control faces more challenges. To stabilize the exchange rate, VND deposit interest rates must remain attractive to encourage holding the local currency. Therefore, the exchange rate will also be one of the factors exerting pressure on deposit interest rates in the near future.
In another development, on August 4, 2025, the SBV held a conference to implement solutions for stabilizing deposit interest rates and reducing lending rates. According to the central bank, the average newly incurred deposit interest rate stands at 4.18% per year, basically stable compared to 2024. The average lending interest rate has fallen to 6.53% per year, down 0.4 percentage point from the end of 2024.
The SBV has required credit institutions to strictly follow the directives of the Government, the Prime Minister, and the central bank to stabilize deposit interest rates; continue cutting operating costs, strengthen digital transformation, and be ready to share part of their profits to lower lending rates in order to support people and businesses in accessing bank credit, thereby promoting economic development.