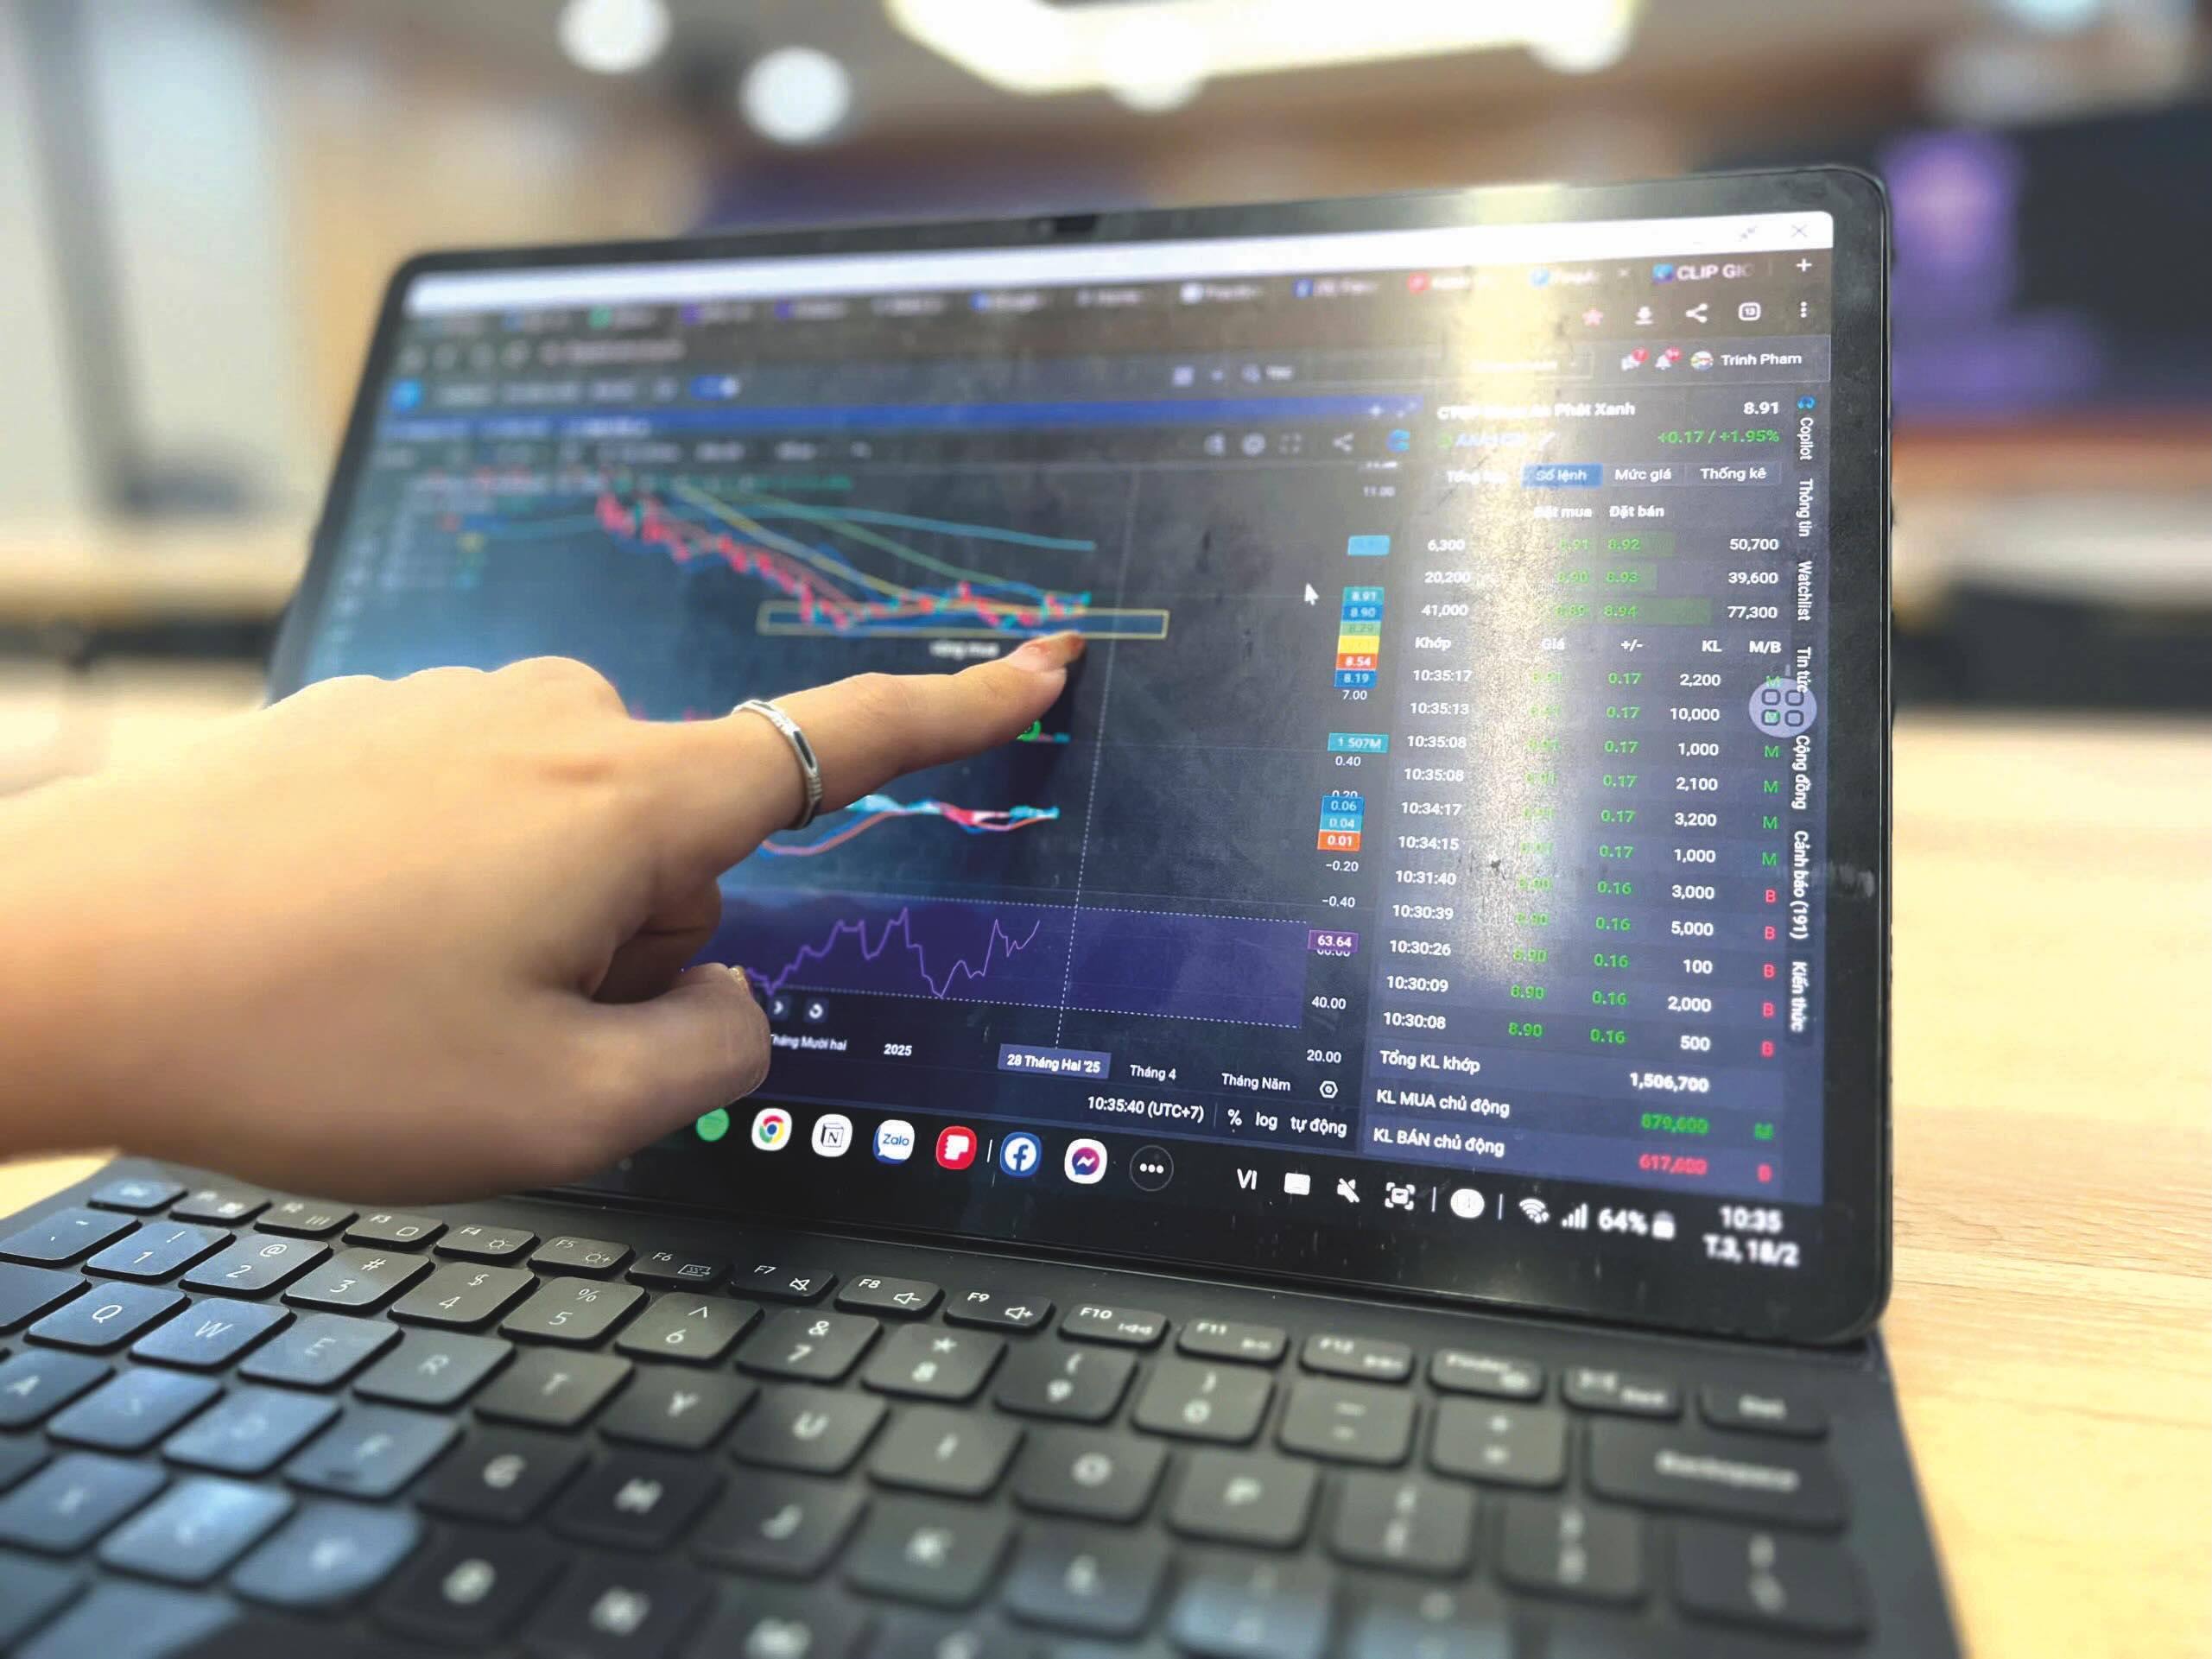
Liquidity in the stock market has dropped markedly in recent weeks. Beyond the negative market developments that have led many investors to temporarily withdraw, are cash flows from securities now being redirected into alternative investment channels?
Liquidity wanes despite higher readings On November 17, the first trading day of the week, the VN-Index surged nearly 19 points, or 1.16%, building on a gain of more than 36 points in the previous week. The resumption of U.S. government operations on November 12 after a 43‑day shutdown, together with President Donald Trump’s November 14 executive order exempting a range of agricultural imports from reciprocal tariffs, provided a boost to global stock markets. These developments also extended a positive influence on Vietnam’s market performance. Domestically, the National Assembly has endorsed an economic growth target of at least 10% for 2026, fueling expectations that fiscal and monetary policies will remain expansionary, with an even greater degree of easing. The recent recovery in trading sessions has fueled hopes that the short-term market correction has ended and that the VN-Index is now building fresh upward momentum. However, trading volume failed to keep pace with the market’s gains, indicating that investors remained cautious. Specifically, the volume of shares traded on the HOSE between November 10 and 14 totaled 3.21 billion—just 54% of the 20‑week average of nearly 5.93 billion shares—and represented a decline of more than 21% from the preceding week. Overall, liquidity in the first half of November fell 29% compared with the average level in October. Compared with the all‑time high trading volumes on the HOSE—reaching 1.8–1.9 billion shares per day in August and 1.3–1.4 billion in July—the current average of only about 650 million shares per session underscores the extent to which market liquidity has deteriorated. As a result of the ongoing market correction since mid‑October, many investors remain on the sidelines, waiting for clearer signals. While the VN‑Index did stage rallies in several sessions during the second week of November, the weekly chart indicates that the index is still in the early stages of a correction phase.
It is noteworthy that the VN‑Index’s recovery momentum during the second week of November and the first trading day of the third week remained heavily reliant on a handful of large‑cap stocks. The 10 most influential stocks together contributed 26 points to the 36‑point gain recorded between November 10 and 14, with VIC of Vingroup alone accounting for more than 10 points.
The persistent net selling trend among foreign investors has continued to weigh on market sentiment. From November 5 to 17, foreigners recorded nine consecutive sessions of net selling, with a total value exceeding VND7.3 trillion across all three exchanges. Notably, during the second week of November alone, foreign investors net sold approximately VND2.74 trillion. This marked the 17th straight week of net selling and pushed the cumulative value since the start of the year to more than VND134.07 trillion—surpassing the previous record high of VND92.6 trillion set in 2024.
The destination of cash flows
Competitive savings interest rates have evidently diverted part of the cash flow away from the stock market once profits were realized. After signs of rate increases in October, a growing number of banks have raised deposit rates further since early November, including Sacombank, VPBank, MB, GPBank, BVBank, Techcombank, BaoViet Bank, PVCombank, LPBank, and KienlongBank, among others.
Notably, for savings with maturities of less than six months, several banks have set interest rates close to the regulatory ceiling of 4.75% per annum. In contrast, competition in the 6–12‑month segment is currently intense, as many lenders are offering higher rates to customers with large deposits, given that these terms are not subject to any interest rate cap.
In a recent report, Vietcombank Securities (VCBS) forecast that deposit rates are likely to rise further, driven by two key factors. First, full‑year credit growth is expected to reach 18–20%, creating strong capital demand toward the end of the fourth quarter. Second, exchange‑rate risks between the U.S. dollar and the dong remain elevated as the import season enters its peak, compelling banks to maintain attractive dong interest rates in order to stabilize funding sources.
The relentless escalation of the exchange rate in recent months has also weighed on the stock market, prompting foreign investors to continue net selling and diverting capital toward exchange‑rate swing trading. Although deposit rates for the U.S. dollar remain capped at 0%, some customers have opted to mortgage their savings books to borrow dong at low interest rates and reinvest it into banks at higher rates.
In addition, cash flows appear to have shifted toward alternative assets such as gold and real estate. While the gold market has experienced considerable volatility year‑to‑date, the real estate sector is showing signs of revival, supported by projects that have resolved legal obstacles and by the current emphasis on infrastructure development.
That said, investors should also keep an eye on small‑ and mid‑cap stocks while major cash flows remain on the sidelines. The sharp rally from late April to mid‑October was largely driven by large‑cap names, yet many companies in the small‑ and mid‑cap segment continue to offer attractive valuations and considerable growth potential—particularly those with strong financial foundations and improving business performance.
It is worth highlighting that small‑ and mid‑cap stocks are closely tied to sectors such as domestic consumption, small‑ and medium‑scale manufacturing, logistics, technology, materials, retail, and renewable energy—areas that directly benefit from the economy’s strong growth momentum. With credit growth reaching 15% in the first 10 months of 2025, import‑export turnover rising 17.4% year‑on‑year, and the manufacturing and processing sector expanding by 10.5%, many small‑ and medium‑sized enterprises are recovering at an even faster pace than leading corporations.
Moreover, the highly volatile nature of small‑cap stocks—though riskier—can be well suited to a low‑liquidity market environment. In periods when major cash flows temporarily withdraw, individual investors, with their greater flexibility, can more easily generate price movements in this segment. Stocks with compelling narratives—such as capacity expansion, market growth, restructuring, or digital transformation—often carry stronger appeal and are more likely to trigger short‑term waves.
However, as opportunities are always accompanied by risks, small‑ and mid‑cap stocks remain vulnerable to price manipulation, limited transparency, and weak trend sustainability. For this reason, investors should be more selective, prioritizing businesses that demonstrate genuine profit growth, maintain low debt levels and healthy cash flows, and operate in industries with solid prospects in the period ahead.